
By Uladzimir Leuchankou, founder of Signal2Forex · 7 November 2026
What is an algorithm in the currency market? A program that trades faster than a person can click? I suppose that is an answer too. But for me there are two different programs behind this word, and they do opposite jobs. Algorithmic and high frequency trading are often named together, as if they were one thing.
FX execution algorithms are programs that cut one large order into many small ones — the goal is a fair average price without moving the market. A high frequency trading algorithm does something else. It quotes a buy price and a sell price all day, holds a position for seconds or less, and earns a small part of the spread each time. The first program is slow on purpose. The second one lives on speed.
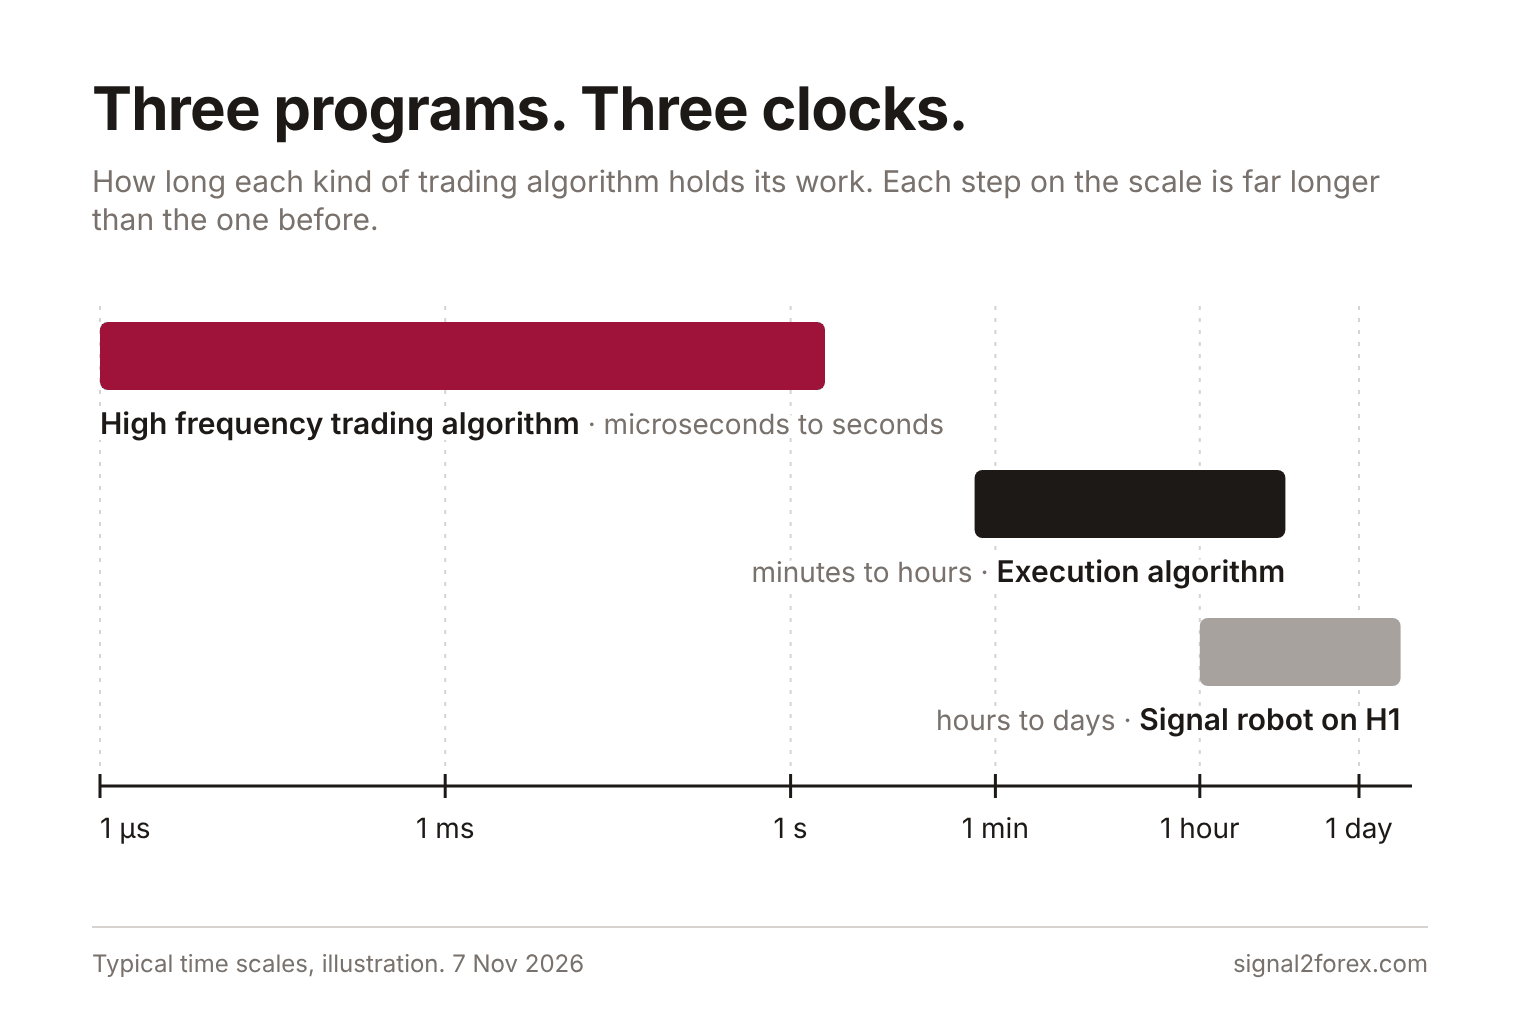
There is a third program too, and it is the one most of us run at home. This is the signal algorithm — a robot that decides what to buy and when. My own robots are of this kind. So before the details, here are all three in one table.
| Program | Its job | How long it works |
|---|---|---|
| Execution algorithm | Buys or sells a fixed amount at a fair average price | Minutes to hours |
| High frequency trading algorithm | Quotes both sides and earns a part of the spread | Microseconds to seconds |
| Signal algorithm — a retail robot | Decides what to trade and when | Hours to days |
Three numbers, one confusion
Most articles say that about 80% of currency trading is done by algorithms. This page said it too, in its older version. I do not agree with that number anymore. I went back to the sources, and the number mixes three different things.
The first number is 59%. This is the share of FX turnover that was traded electronically in April 2025, according to the BIS Quarterly Review of December 2025. Electronic means a screen instead of a phone call. It does not mean that a robot made the decision. The same review puts total turnover at $9.5 trillion a day.
The second number is the real 80%. Dealers now match more than 80% of customer trades inside their own books — the BIS calls this internalisation. A bank pairs one client who buys with another client who sells, and the trade never reaches the open market. This is a fact about banks, and it says nothing about algorithms.
The third number is the one that answers the question. In its report FX execution algorithms and market functioning, published in October 2020, the BIS Markets Committee estimated that execution algorithms handle 10–20% of global spot trading. That was about $200–400 billion a day. The report called their use “widespread but not dominant”. I do not know how far the share has moved since then — the BIS has not repeated that survey.
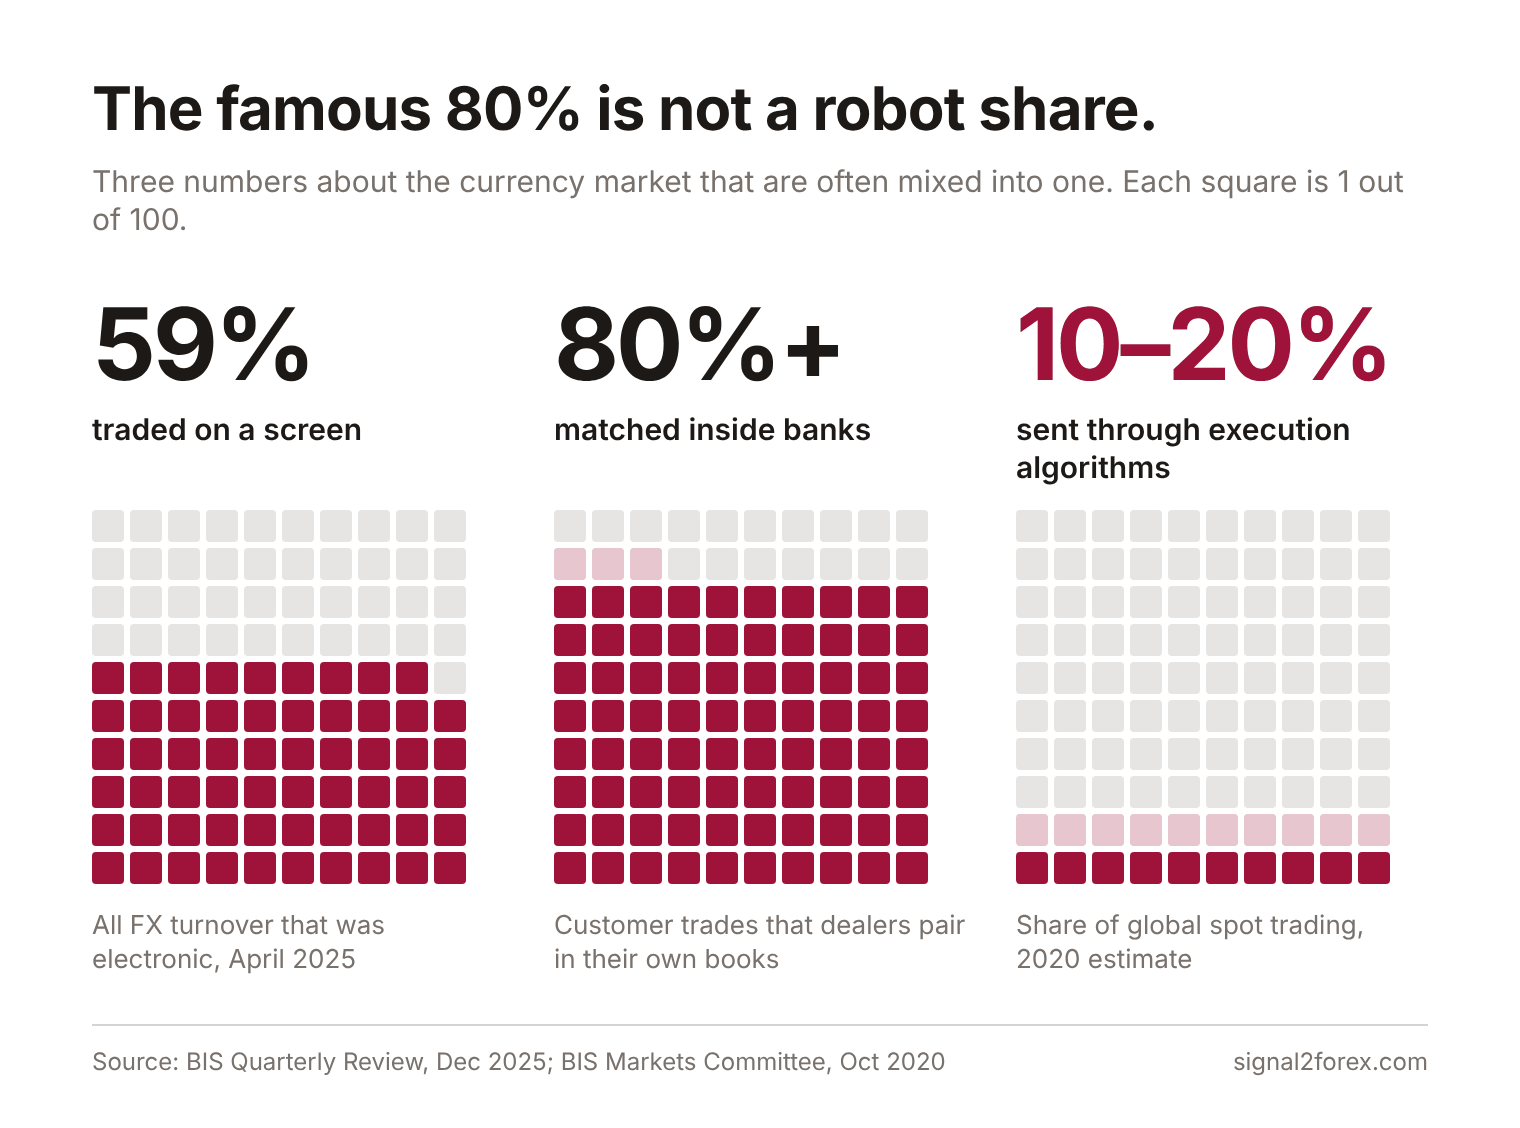
And the fast firms? The BIS counts high frequency traders among principal trading firms. Together with hedge funds they made about 8% of global FX activity in April 2025. So the machines matter, but the picture is not one big 80%. If you read a market statistic, you need to check what exactly it counts.
FX execution algorithms
Think of a pension fund that must buy 50 million euros against the dollar. This is 500 standard lots — one standard lot is 100,000 units. One pip on that size is $5,000. If the whole order hits the market at once, the price moves away from the buyer, and two pips of slippage cost $10,000.
So the fund gives the order to an execution algorithm. The parent order is cut into child orders — for example 50 tickets of 10 lots, one every two minutes. No single ticket is large enough to move the price. This is algorithmic execution in its simplest form. The trade execution algorithms that banks offer to clients are all built on this idea.
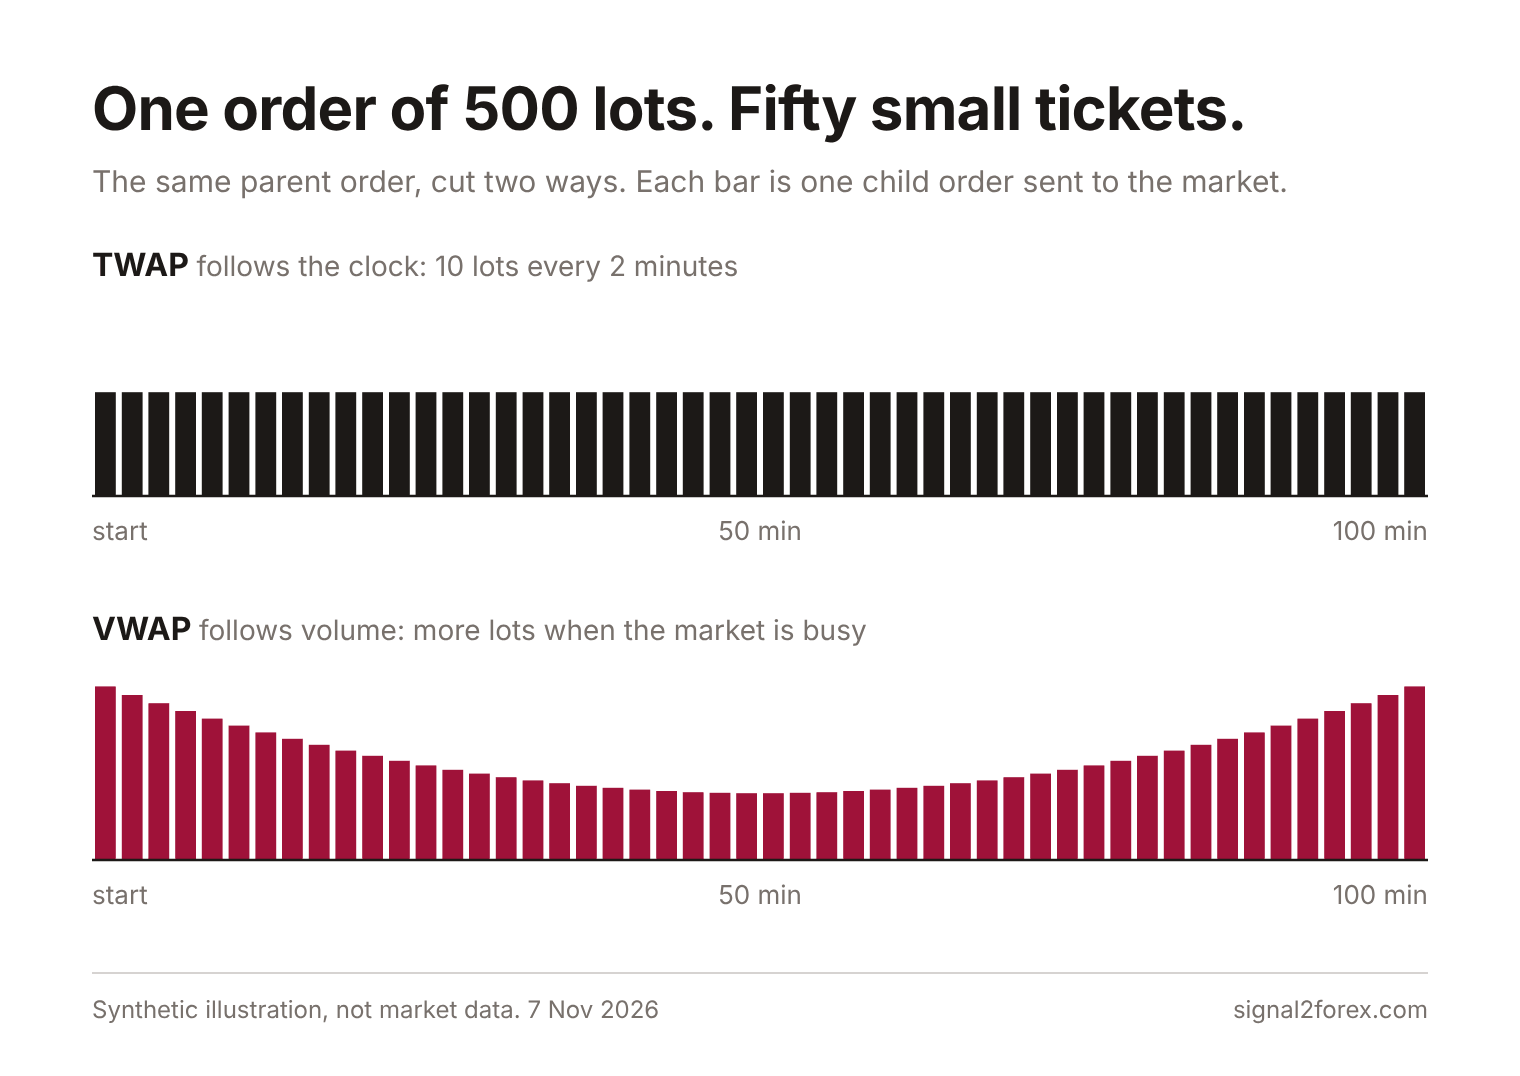
There are several kinds, and they differ in one parameter — what sets the pace. The first kind — TWAP — follows the clock and sends equal parts at equal intervals. VWAP is the second kind — it follows the usual volume of the day and trades more when the market is busy.
Two more are common. A percentage of volume algorithm keeps the order at a fixed share of what the market trades right now. An implementation shortfall algorithm starts fast and then slows down, because it is measured against the price at the moment the order arrived. Banks sell these fx algorithms under their own brand names, but the logic is the same.
Who uses them? Not only investment funds, but also companies and central banks. In the BIS survey some large corporations sent 20–25% of their FX volume through algos, and one central bank sent almost 90%. The trend continues. On 28 April 2026 Bloomberg reported a Crisil Coalition Greenwich study — roughly a quarter of buy-side trading desks use or plan to use non-bank firms for FX execution, and much of that goes through fx algos.
There is a cost, and the BIS report says it openly. With algo execution the risk moves from the dealer to the client. A bank that quotes one price for 50 million euros carries the risk itself. A client who slices the order over three hours carries the market move for three hours. This is not only a tool for a better price, but also a decision to hold risk longer.
One detail I like as a programmer. The BIS shortens execution algorithms to EAs. In my MetaTrader terminal EA means Expert Advisor. Same two letters. The BIS kind asks how to trade, and mine asks what to trade.
High frequency trading algorithm
What is a high-frequency trading algorithm? It is a program that posts a buy price and a sell price at the same time, thousands of times a day. When both sides are filled, the firm keeps the difference — often less than one tenth of a pip. Then it does the same again.
Such hft algorithms need several things, and all of them are about speed. The first — a server in the same data centre as the trading venue. Then a data line that is a little faster than the line of the next firm. And code that cancels a quote the moment the market moves. Most quotes are cancelled before anyone trades on them. For hft algo trading this is normal work and not a fault.
Do high frequency trading algorithms help the market or harm it? Critics say this liquidity disappears exactly when it is needed. I had the same doubt. But April 2025 was a hard test — US tariff news and record volume in the same month. The BIS looked at that month and found that bid-ask spreads stayed close to normal. The fear of prices that vanish under pressure did not come true.
I do not know whether this holds for every pair and every hour. A thin pair at 22:00 GMT is a different market from EUR/USD at noon. If you trade outside the busy hours, you need to look at the spread on your own screen.
Noon on 5 November
Here is a fresh case. On 5 November 2026 at 12:00 GMT the Bank of England raised Bank Rate from 3.75% to 4.00%, with an 8–1 vote. GBP/USD traded near 1.35 that morning. The rise was expected, so there was no shock.
But the first seconds of such a decision still belong to machines. Before the release, fast market makers often widen their quotes or pull them — nobody wants to hold a price that can be wrong a millisecond later. Many users pause their execution algos over the announcement. Then the text arrives, programs read it, and the quotes come back.
For my robots this minute is simple. They trade on the H1 chart and do not read news. Before each order the code compares the current spread with a limit in the settings — if the spread is wider, the order waits. The robot does not know what the Bank of England said. It only sees that the spread is too wide. If your strategy needs a normal spread, you need to check the spread itself.
A retail trader’s place
Can you run a high frequency algo trading strategy from a home terminal? No. Look at the lower right corner of MetaTrader — the terminal shows the delay to the broker’s server in milliseconds. Fast firms count in microseconds, a thousand times smaller. And your order goes to a broker first, not to the venue. An hft algo sold for a retail platform cannot change this distance.
So the high frequency trading vs algorithmic trading question has a short answer for us. All high frequency trading is algorithmic, but most algorithmic trading is slow. HFT vs algorithmic trading is a difference of time scale and of job, and only the slow part is open to a private trader.
What a retail trader really uses is algorithmic trading signals — rules that say buy, sell or wait. This is where I work. Forex V Portfolio is 28 robots on 14 pairs, all on H1, and every one of them is a signal algorithm. The live account behind them runs on a public YouTube stream. Speed is not a parameter there. An order that arrives 50 milliseconds late on an hourly bar changes nothing.
What changes the result is cost. On a $10,000 account with 0.10 lot, one extra pip of spread or slippage costs $1 per trade. On a $100 cent account with 0.10 cent lot it costs 1 cent. It looks small. Over 300 trades a year it is $300 or $3 — this is 3% of either account. If you count pips, count them in money too.
There is one more thing to take from the big players. They measure every order after it is done — the price they wanted against the price they got. I wrote about these tools in the article on FX execution management systems. A private trader can do a simple version of the same check. Compare the price on the signal bar with the fill price in the account history, trade by trade.
Execution algorithms, high frequency firms, signal robots, spreads, the minute of a rate decision — all this is one market seen on different time scales. I cannot be faster than a server in a data centre, and I do not need to be. The more clearly you know which time scale you trade on, the steadier your results will be.
Figures in this article come from the BIS Markets Committee report FX execution algorithms and market functioning, October 2020; the BIS Quarterly Review, December 2025, with the results of the 2025 Triennial Survey; the Bank of England decision of 5 November 2026; Bloomberg, 28 April 2026.
Uladzimir Leuchankou is a software engineer with a BSc in Finance and the founder of Signal2Forex. He writes the robots sold on this site, including Forex V Portfolio, and runs them on a live account that is streamed on YouTube. The notes on the spread limit and hourly bars in this article come from that code. Contact — forexfactory1shop@gmail.com, MQL5 profile.



 Signal2forex.com - Best Forex robots and signals


