
By Uladzimir Leuchankou, founder of Signal2Forex · 7 November 2026
What is currency volatility? Just a measure of how far a price moves and how fast? I suppose that is an answer too. But for me currency volatility is the size of a normal day for one pair — a number in pips that I need to know before I set a stop or choose a lot.
Last Friday gave a fresh example. On 6 November 2026 the US jobs report came out at 13:30 GMT. Over the 20 days before it, USD/JPY had moved about 86 pips a day. On that Friday it moved about 125.
| Measure | Pips | What it tells you |
|---|---|---|
| Average day, last 20 days | 86 | The normal size of a day — historical volatility |
| Move that options priced for the night | 141 | What the market expected — implied volatility |
| Low to high on the day | about 125 | What happened |
Two of these numbers — the average and the priced move — come from StoneX option data published on the morning of 6 November. The third is my own count — from the low near 157.25 in the Asian session to the high near 158.50 after the report.
One Friday in Numbers
And the report was a surprise. The US Bureau of Labor Statistics counted 165,000 new jobs in October. Economists had expected about 65,000. Unemployment fell to 4.1%. In the first minutes USD/JPY was up 72 pips on the day, at 158.38.
So was this a volatile day? Against the average of 86 pips — yes, the day was almost half as large again. Against the 141 pips that options had priced — no, the day was smaller than the market feared. This is why I never call a day volatile without saying which number I compare it with.
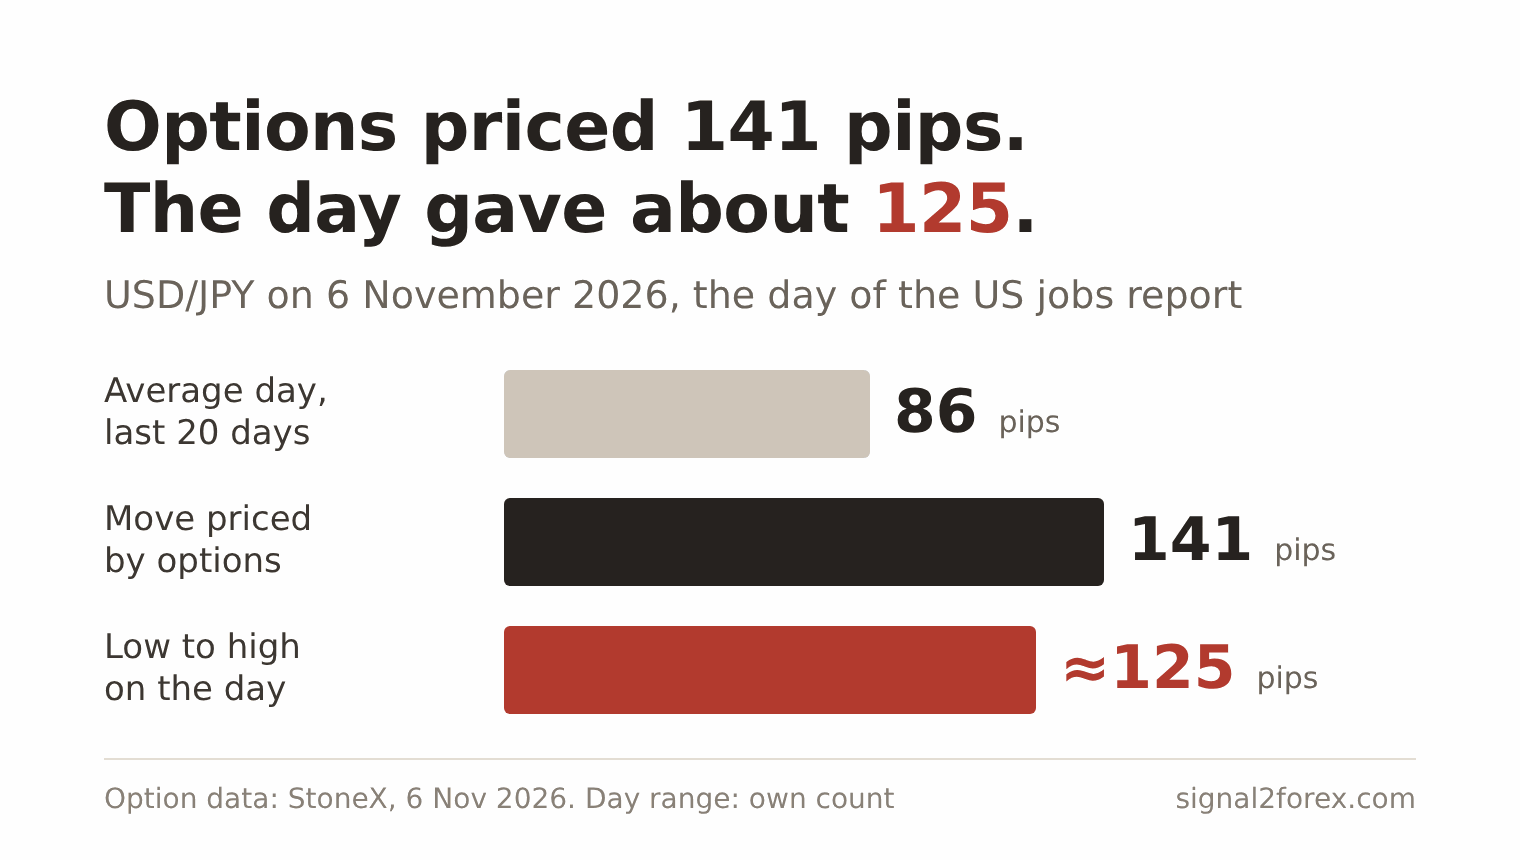
In money the same day looks like this. One pip of USD/JPY on one standard lot — 100,000 units — was worth about $6.31 at a rate of 158.40. A move of 125 pips was about $789 on one standard lot and $7.89 on 0.01 lot. If you trade a $100 cent account, you need this number in dollars before the report, and you cannot get it after.
Two Kinds of Volatility
What is volatility in forex when you open a trading book? There are two kinds, and the table above shows both. Historical volatility is counted from prices that already exist — the high, the low and the close of past days. Implied volatility is taken from option prices. It shows how large a move traders are ready to pay protection against.
This is the currency volatility meaning I use in my own work. Historical volatility is a parameter — I can count it, test it and put it into a robot. Implied volatility is a warning. My robots read prices and do not read options, so for me the implied number works like a calendar. It tells me that a large day may come, and no more than that.
There is another level — currency market volatility as a whole. The Bank for International Settlements measured the market in April 2025, in the weeks after the US tariff announcements. Trading reached $9.6 trillion a day, 28% more than in 2022, and the BIS noted that the survey took place “amidst elevated FX volatility”.
For me this is the main thing about fx volatility. It is the time when the market trades most, and it cannot be called a fault of the market. Large days and large volume come together.
The Average True Range
If I could keep only one forex volatility indicator, it would be the Average True Range, or ATR. Welles Wilder described it in 1978 in his book New Concepts in Technical Trading Systems. It is built into every terminal — the MetaTrader 5 help page gives the same formula.
The true range of a day is the largest of three distances. First comes the distance from the high to the low. The second — from the previous close to the high. And the third — from the previous close to the low. Why three? Because a pair can jump between one close and the next open, and a simple high minus low loses that jump.
Take last Friday again. Thursday closed near 157.70. Friday’s high was near 158.50 and the low near 157.25. High minus low gives 125 pips, previous close to high gives 80, previous close to low gives 45. The true range is 125.
Wilder then smooths it over 14 days — the old value times 13, plus the new range, divided by 14. With 86 as the old value I get 86 × 13 + 125 = 1,243, and 1,243 ÷ 14 is about 89 pips. One large day moved the average by 3 pips.
This is what I like about ATR — it does not panic. Bollinger Bands and standard deviation show the same thing in another form, and I use them less often. A longer look at the indicator is in the article on how to measure volatility with ATR.
From Range to Lot
How do you trade volatility if you are not an option desk? For me the answer is simple — I let it set the stop and the lot. The range goes in first, and the size of the trade comes out last.
Here is the arithmetic with Friday’s numbers. I take 86 pips as the normal day and put the stop at 1.5 of it — 129 pips. On a $10,000 account I risk 1%, which is $100. One pip on 0.01 lot of USD/JPY was worth about $0.063, so 129 pips cost $8.14 for each 0.01 lot. Then $100 ÷ $8.14 gives 12 steps of 0.01 — a lot of 0.12.
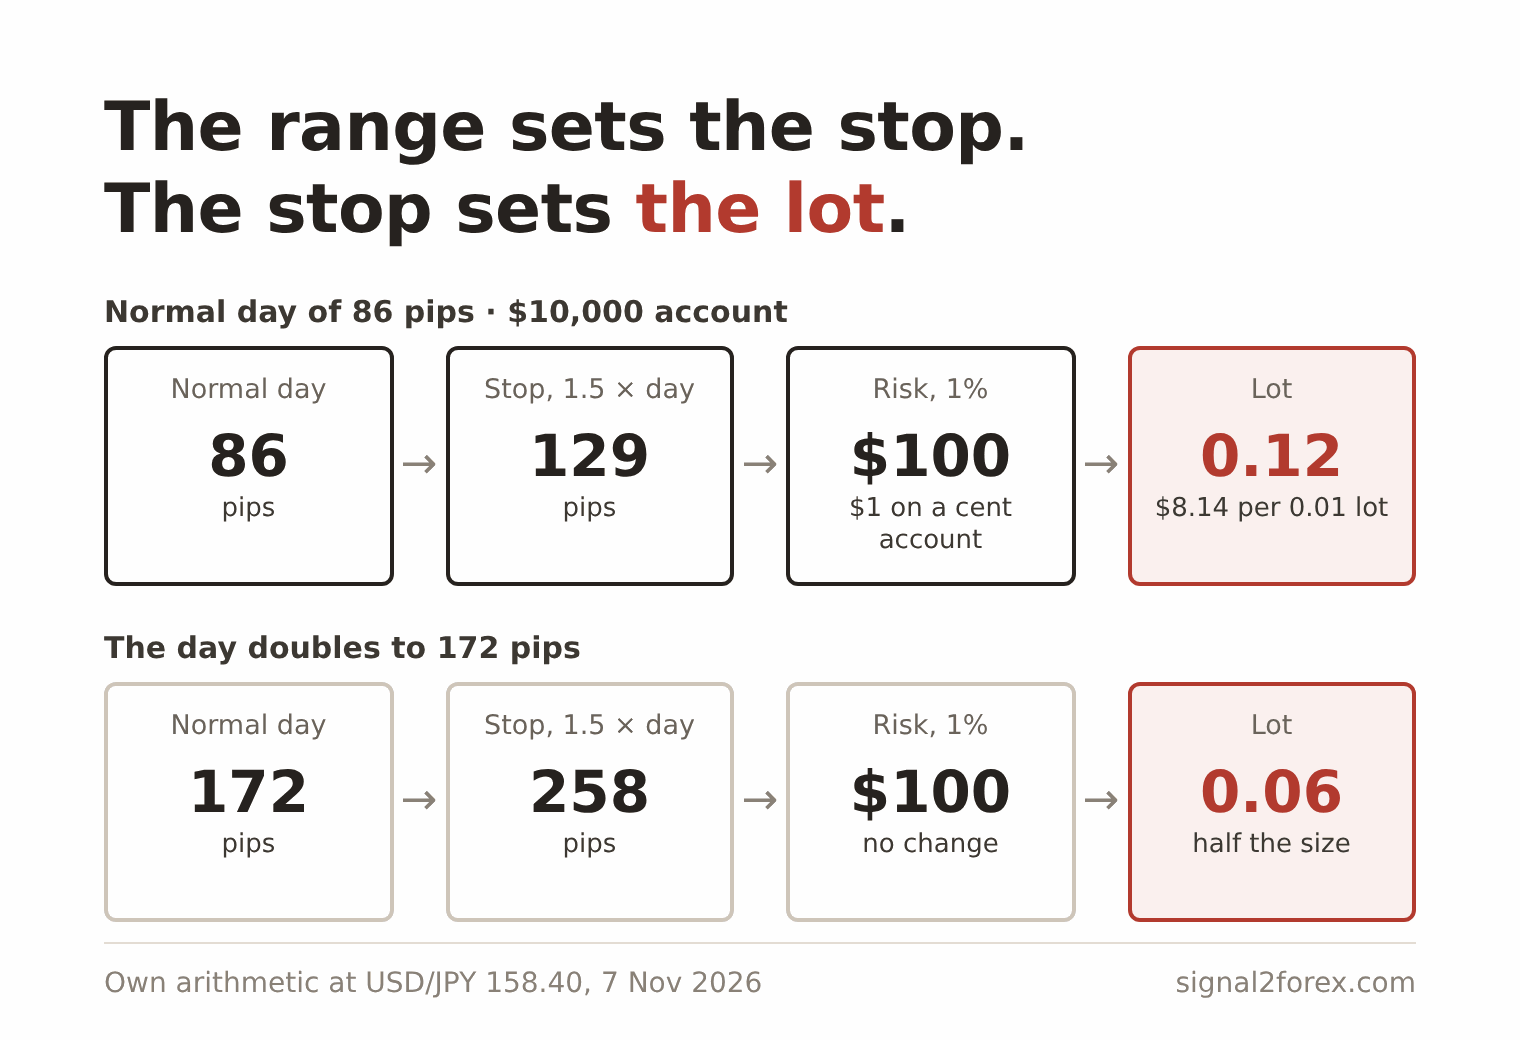
On a $100 cent account the same steps give a risk of $1 and a lot of 0.12 in cent lots. And if the normal day doubles to 172 pips? The stop becomes 258 pips and the lot falls to 0.06. The loss on a bad trade stays close to $100, or $1 on the cent account. If you need a refresher on the pip value itself, it is in my article on what a pip is.
I do not know a better use of volatility in forex than this one. When the day gets larger, the lot needs to get smaller.
Currency Volatility by Pair
Which is the most volatile currency? People ask it often, and the usual answer is a table of pips. This page had such a table before. I removed it — I could not confirm its numbers with a dated source, and the lists I checked this week disagree with each other. One gives USD/JPY 40 to 80 pips a day, another gives 80 to 120.
There is a second problem with such tables. Pips of different pairs are not equal. A day of 86 pips on USD/JPY at 158.40 is 0.54% of the price. The same 86 pips on EUR/USD at 1.12 would be 0.77%. So the volatile currency meaning that works for me is a large normal day in percent of price. The count of pips can mislead.
Between currencies volatility differs for reasons that change slowly. Pairs of two large economies with close interest rates — EUR/GBP, EUR/CHF — are usually the quiet ones. EUR/USD and USD/JPY sit in the middle. Crosses with the pound and the yen move more. Currencies of emerging markets such as the rand, the lira and the Mexican peso move most, and their spreads are wider too.
The volatility of currency pairs also depends on the hour — the same pair is quiet in the late US evening and loud when London and New York overlap. A daily number hides this, so I also look at the hour.
Any currency volatility meter or forex volatility chart on a website shows this picture for somebody else’s broker and server time. A currency volatility chart for your own account is one indicator on your own daily chart. Our Forex V Portfolio trades 14 pairs on the H1 chart for this reason — large days come to different pairs at different times, and I would not want all the risk on one of them.
Events Without Movement
Most articles say that news makes forex volatility. From what I saw last week, this is only half true. There were three large events in five days, and they moved prices very differently.
The first event was the US midterm elections on 3 November. Democrats won both chambers of Congress. The market had to change its prices, and the dollar index fell by about 0.8% — MUFG Research wrote on 6 November that the loss was then quickly reversed.
The second was the Bank of England. On 5 November it raised Bank Rate from 3.75% to 4% by eight votes to one. A rate rise sounds like a large event. The pound stayed near $1.35 and closed the day almost where it opened. Everybody had expected the rise, so there was nothing left to move.
The third was the jobs report, with a gap of 100,000 jobs between the forecast and the fact.
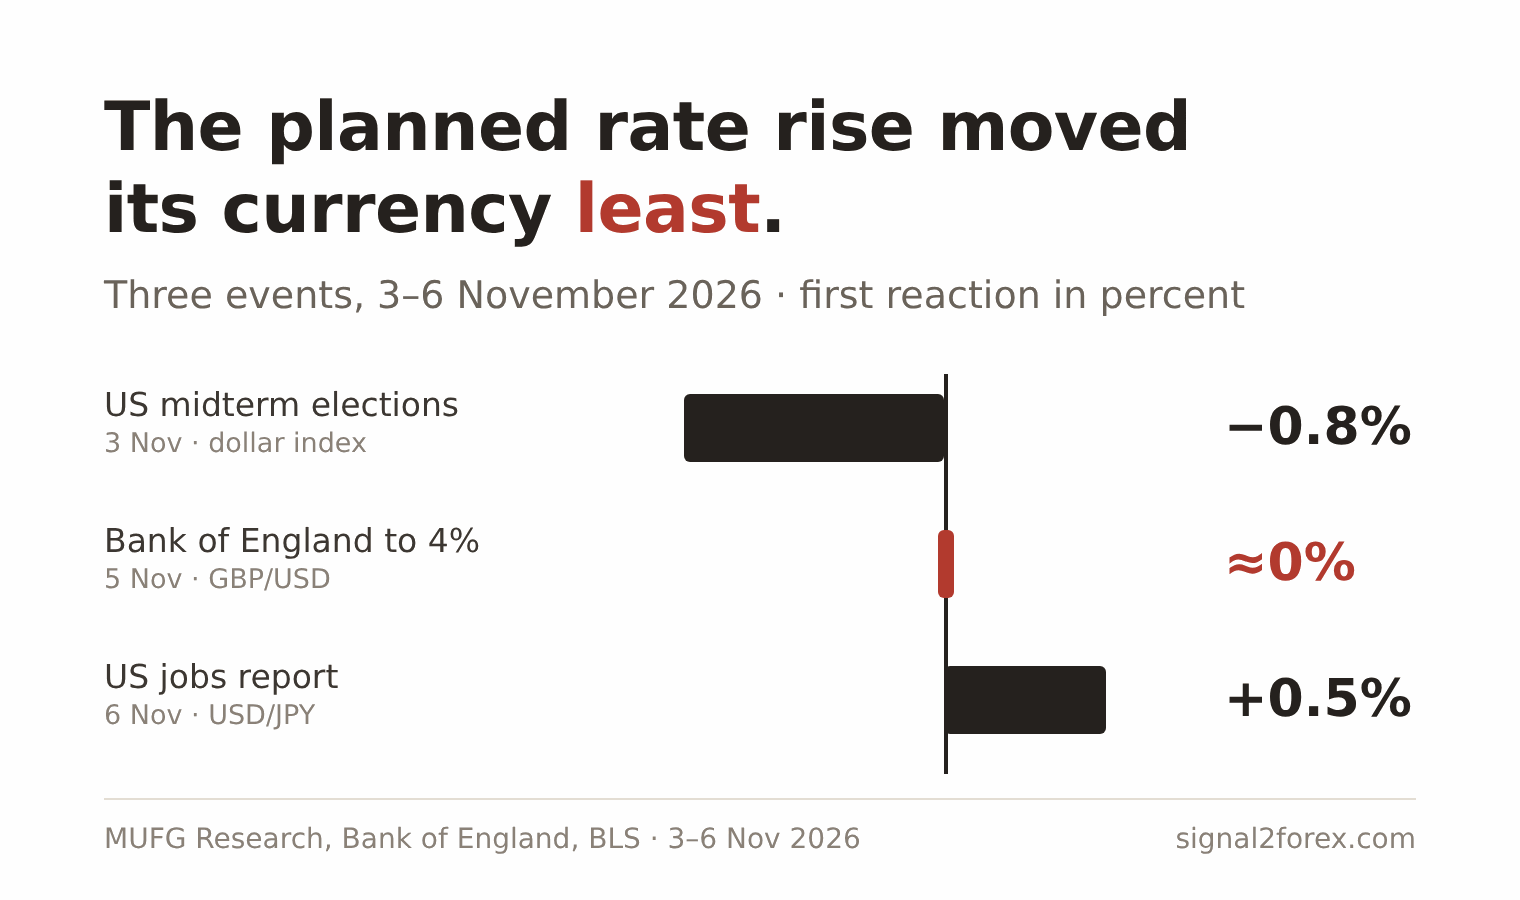
So what makes forex trading volatility? The surprise does. An event that everybody expects is already inside the price. How a central bank prepares the market is a topic of its own, and I covered it in the article on hawkish and dovish policy.
One more thing that I watch around a report is the spread. A large candle is only part of a high-volatility forex day — the broker also widens the spread in the minute of the release. My robots have a spread filter for this.
It is a parameter, and when the spread is above it, the robot does not send a new order. The real account is streamed live on YouTube, so anybody can watch how it behaves around a report. A filter costs me a few trades and saves me from the worst prices.
High Days and Low Days
Is high volatility good for a trader? Many guides say yes — more movement, more chances. I do not agree with this in full. A larger day gives a larger target and a larger stop at the same time. If the lot stays the same, the only thing that really grows is the loss on a bad trade.
Low volatility has its own trap. After a week of small days the stop looks too wide, and you want to move it closer and add to the lot. Then one report brings the normal day back.
I do not know whether next week will be large or small — the US inflation report is on the calendar, and the result is not known to anybody. So I change nothing by feeling. For that I have the ATR — it changes the numbers for me.
The normal day in pips, the true range with its three distances, the stop at one and a half ranges, the lot that follows from the stop, the percent of price instead of the pip count, the surprise instead of the event — all this is one habit. The more often you measure the normal day of your pair, the steadier your risk stays on the day that is not normal.
Figures on this page were checked on 7 November 2026 against the US Bureau of Labor Statistics jobs report of 6 November, the Bank of England decision of 5 November, the BIS Triennial Survey of April 2025, the MUFG Research FX Weekly of 6 November and the MetaTrader 5 help. The ATR formula is from Welles Wilder, New Concepts in Technical Trading Systems, 1978. Trading currencies with borrowed money can lose more than a small account holds.



 Signal2forex.com - Best Forex robots and signals


