
By Uladzimir Leuchankou, founder of Signal2Forex · 18 November 2026
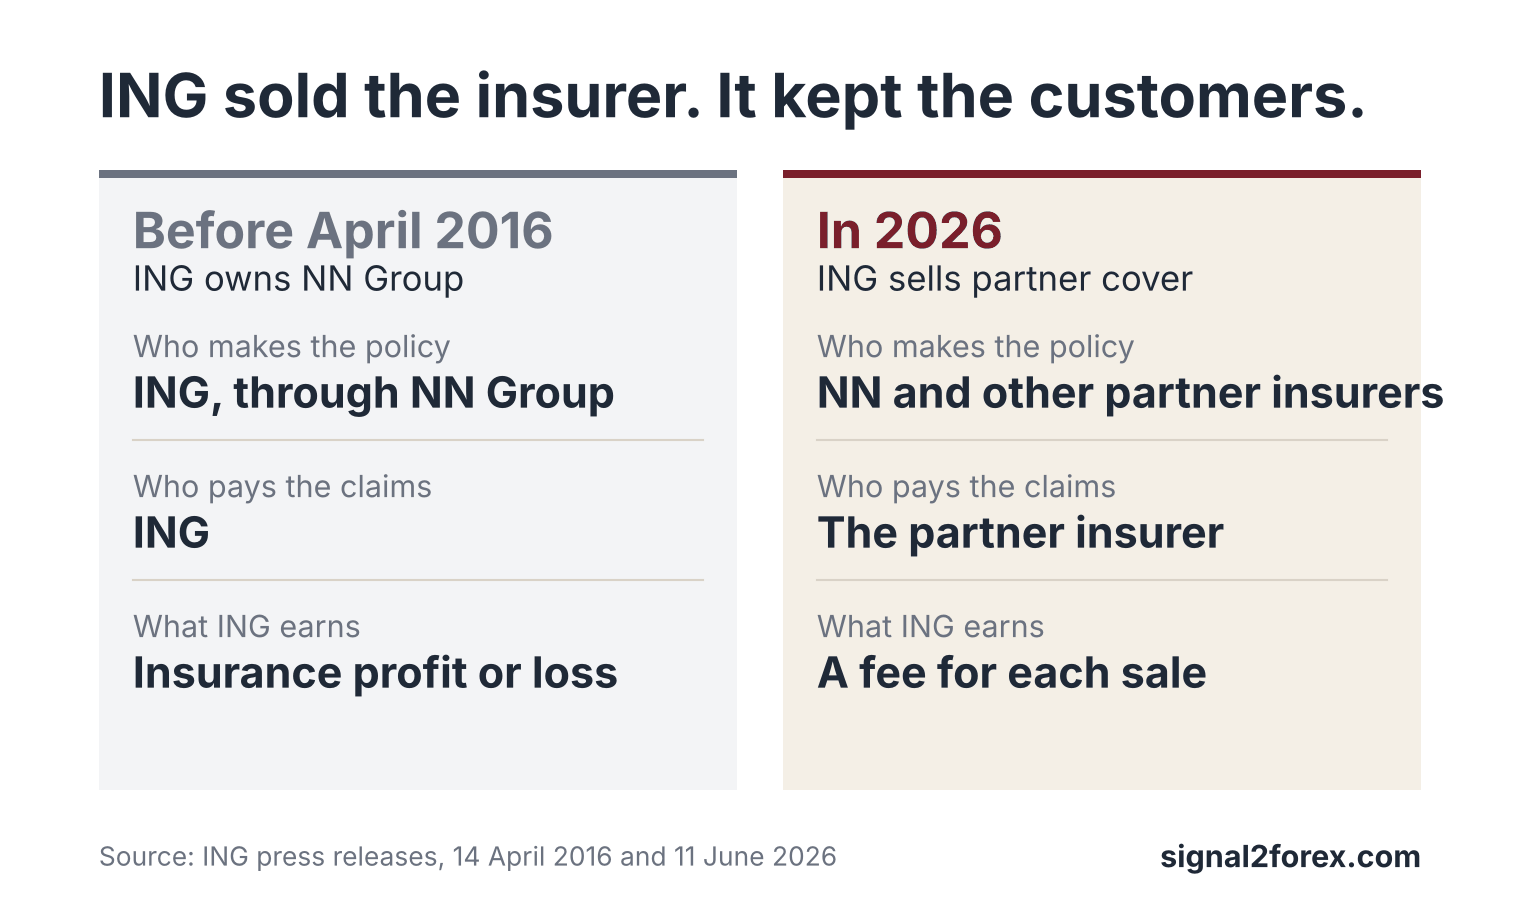
What is ING insurance? A policy for your car, your home or your loan that you buy inside the ING app. I suppose that is an answer too. But for me ING insurance is a different thing — a bank that sells cover made by other companies and keeps a fee for every sale. ING has not owned an insurer since April 2016.
This page first appeared in July 2018, one month after ING signed a deal with the French insurer AXA. The question then was why ING is turning back to insurance two years after it left. I rewrote the page in November 2026. Eight years of ING’s own reports now answer that question with numbers.
| Date | What ING did | Who carries the risk |
|---|---|---|
| October 2008 | Took €10 billion of state aid and agreed to sell its insurers | ING, as owner |
| April 2016 | Sold its last 14.1% of NN Group | NN Group |
| June 2018 | Signed with AXA for six countries | AXA |
| November 2021 | Stopped the global AXA platform | Local partners |
| June 2024 | Extended the NN deal in Belgium to 2034 | NN |
| June 2026 | Chose bolttech for cover inside subscriptions | Partner insurers |
The forced sale
In October 2008 ING took €10 billion from the Dutch state. The European Commission approved the aid on one condition — ING had to sell its insurance and investment businesses around the world. The bank paid back €13.5 billion by November 2014, interest and premiums included.
NN Group, the old Nationale-Nederlanden, went to the stock exchange in July 2014. On 14 April 2016 ING sold its last 45.7 million NN shares at €30.15 each, about €1.4 billion in total. Ralph Hamers, the chief executive at that time, called the sale “the final step in ING’s repositioning as a leading European bank”. This is the day ING stopped being an insurer.
The AXA deal of 2018
Two years passed. On 13 June 2018 ING and AXA announced an exclusive partnership — one digital platform with property, health and protection cover, sold in the ING app in France, Germany, Italy, the Czech Republic, Austria and Australia. Why did a bank that had just left insurance come back? The reason was in its income.
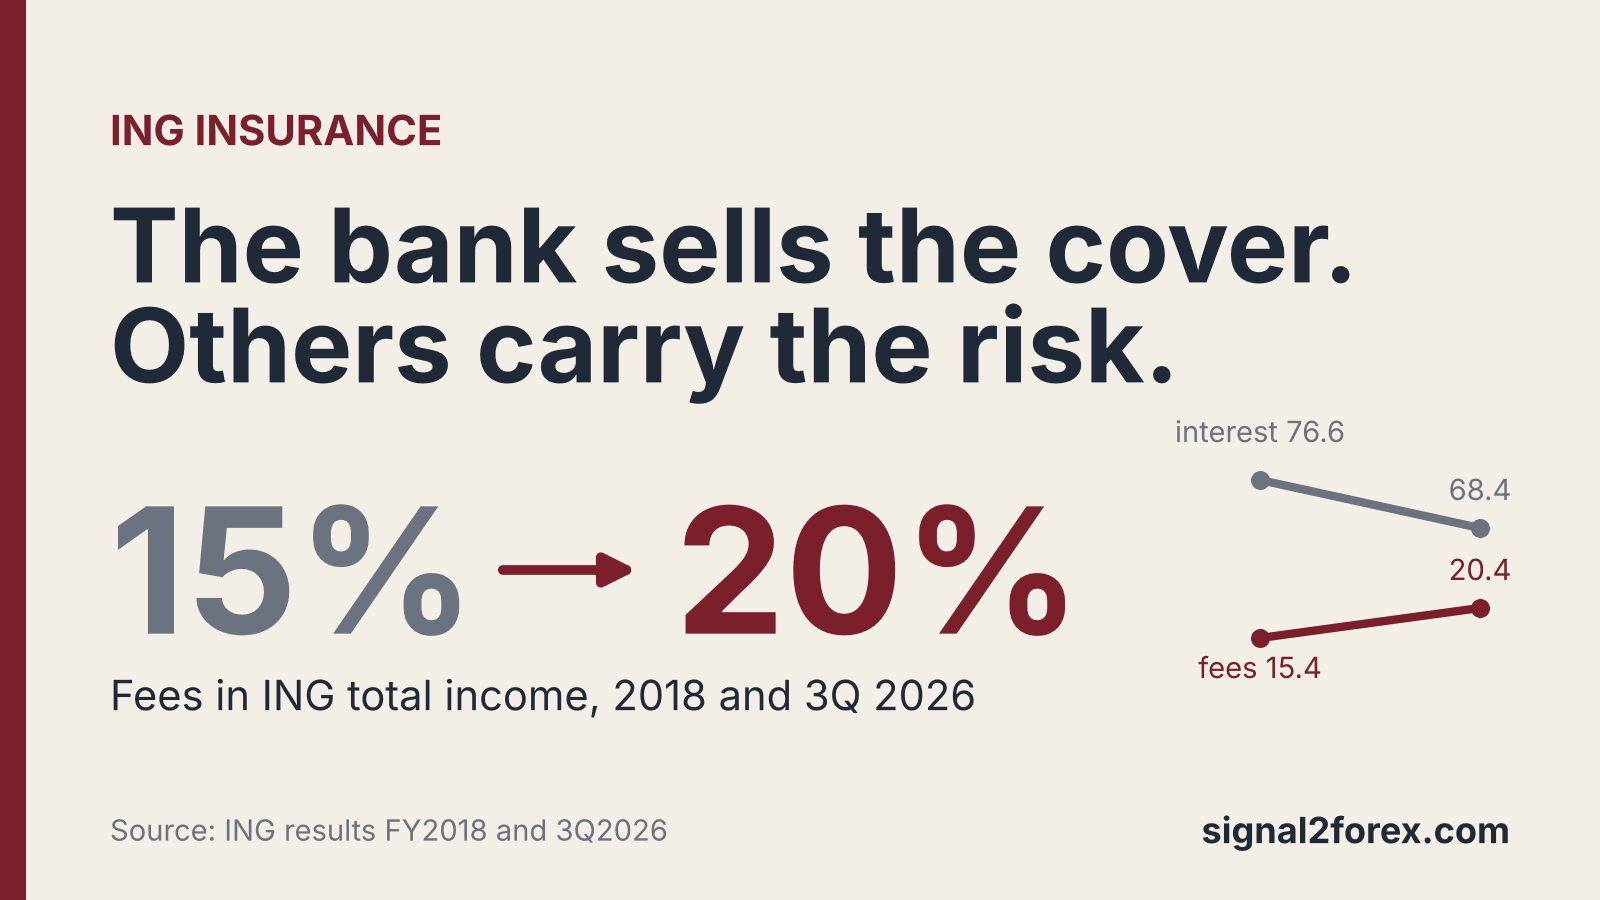
In 2018 ING earned €13,916 million of net interest income out of €18,176 million of total income. Net interest income is the gap between what a bank earns on loans and what it pays on deposits. This is 77 cents of every euro. Fees brought €2,798 million, about 15 cents.
Insurance looked like a way to add fees without adding risk. An insurer collects premiums and pays claims, and one bad year of storms or accidents can take its whole profit. A seller only takes a commission — there are no claims to pay. The commission is smaller than an insurer’s profit in a good year. It is also the same in a bad year.
A bank like that depends on one parameter — the interest rate of the European Central Bank. That rate stood at zero in 2018, and investors did not like it. ING shares ended June 2018 at €12.33, below the €12.85 of equity per share in its books. If you want to see how one rate decision moves a currency, I wrote about it in the pages on interest rates and the forex market and on hawkish and dovish central banks.
I know this problem from my own work. I write trading robots, and a robot that depends on one parameter breaks when the market changes that parameter. This is why our Forex V Portfolio runs 28 advisors on 14 currency pairs. If you live on one source of income, you need a second source before the first one fails.
The end of the platform
The global platform did not last. On 25 November 2021 ING said that it would stop the central platform with AXA and work with insurers country by country. ING also left retail banking in three of the six countries — Austria and the Czech Republic in 2021, France in 2022. Half of the map was gone.
The article that stood on this page in 2018 made two points. The AXA deal would not lift fee income soon, and ING was weaker than banks that still owned an insurer. I agree with the first point and I disagree with the second. The platform failed, yes. But ING did not need to own an insurer — it needed customers who open the app every day and buy more than one product there.
ING insurance in 2026
Today the business is a set of local deals — one country, one partner. In Belgium the partner is NN. On 28 June 2024 ING Belgium and NN extended their agreement until 2034. French-speaking customers there call it ING assurance and look for it on ing.be.
June 2026 brought two more changes. On 10 June ING moved its Dutch customers to monthly subscriptions — one price for a package of banking, insurance and other services. Reuters reported that Belgium, Romania and Poland had the model first. On 11 June ING named bolttech, an insurance technology company, as its partner for cover inside these packages. The cover is live in the Netherlands, Italy, Poland and Belgium.
This is ING bank insurance in its present form. The bank owns the customer and the app, a technology partner connects the products, an insurer carries the risk. How much money does insurance bring on its own? I do not know. ING’s quarterly report shows total fee income and gives no separate line for insurance.
For a customer this changes one practical thing. Your contract is with the insurer and not with the bank, and the insurer pays the claim. Who is that insurer? The name is in the policy documents, and it can be different in each country. If you buy cover in a banking app, you need to read that line before you sign.
The numbers after eight years
I took two reports — the full year 2018 and the third quarter of 2026, published on 29 October 2026 — and counted the share of each kind of income.
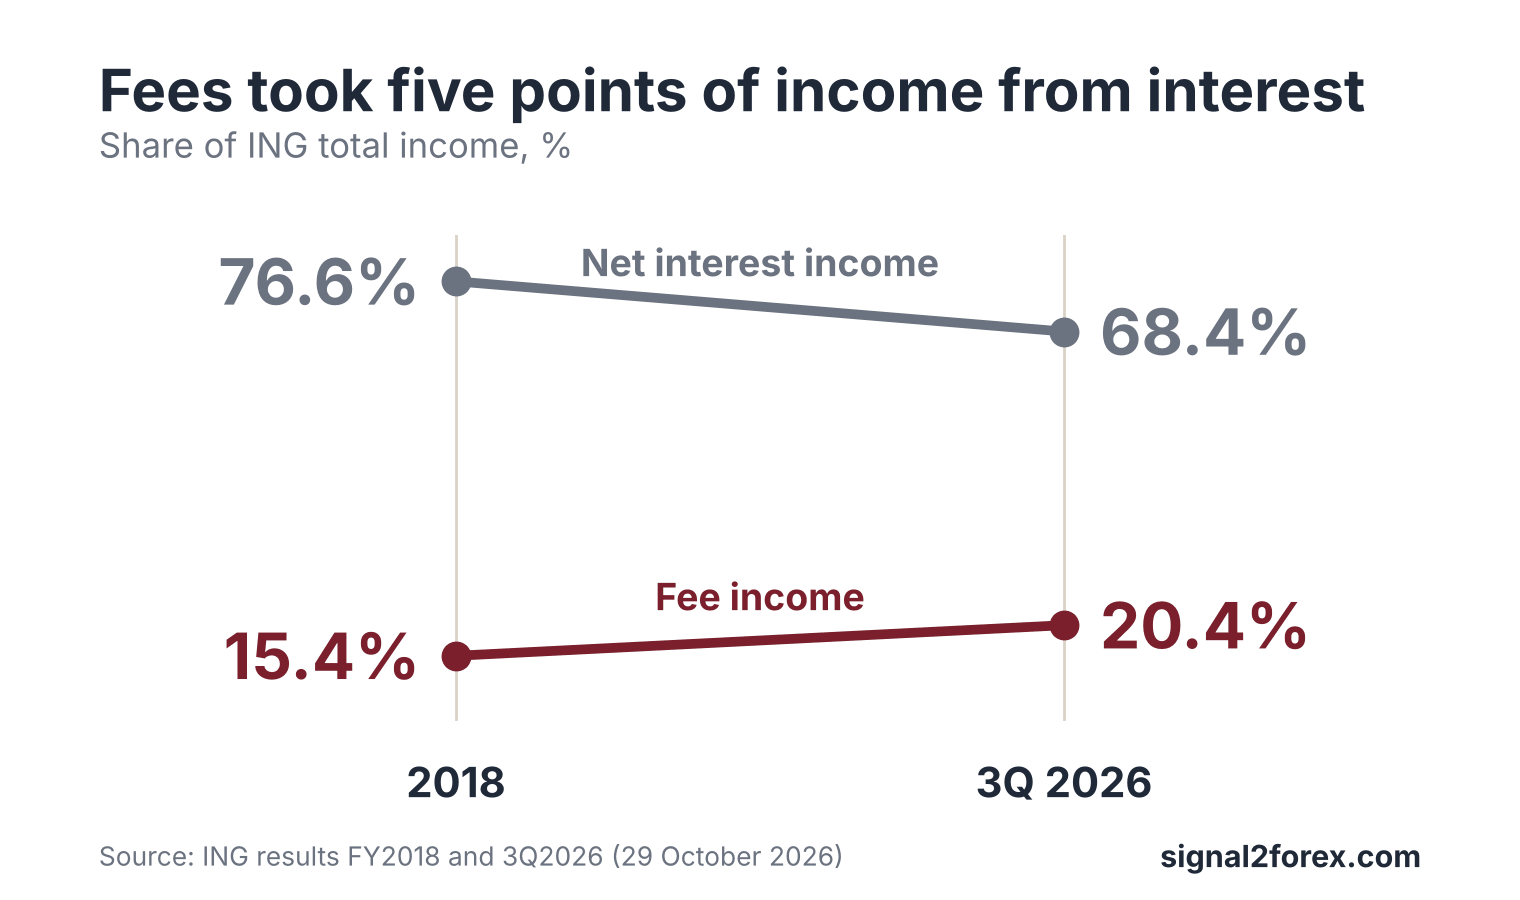
Five points do not look like much. But fee income grew from €2.8 billion in 2018 to €4.6 billion in 2025, a rise of 64%, while net interest income grew from €13,916 million to €14,681 million, only 5.5%. ING now expects about €5 billion of fees in 2026, one year ahead of its plan.
One more number surprised me. The net interest margin was 1.53% in 2018 and 1.47% in the third quarter of 2026 — the bank earns less on each euro of its balance sheet than it did eight years ago. Yet the net result grew from €4,703 million in 2018 to €6,764 million over the last four quarters, about 44% more. More customers, more products for each customer, more fees — all this works together.
The share price followed. ING closed June 2018 at €12.33 and traded near €29.33 on 17 November 2026, a rise of 138%. In money this is about $2,380 from every $1,000, or $238 from $100 on a small account, before dividends and before any change in the euro against the dollar.
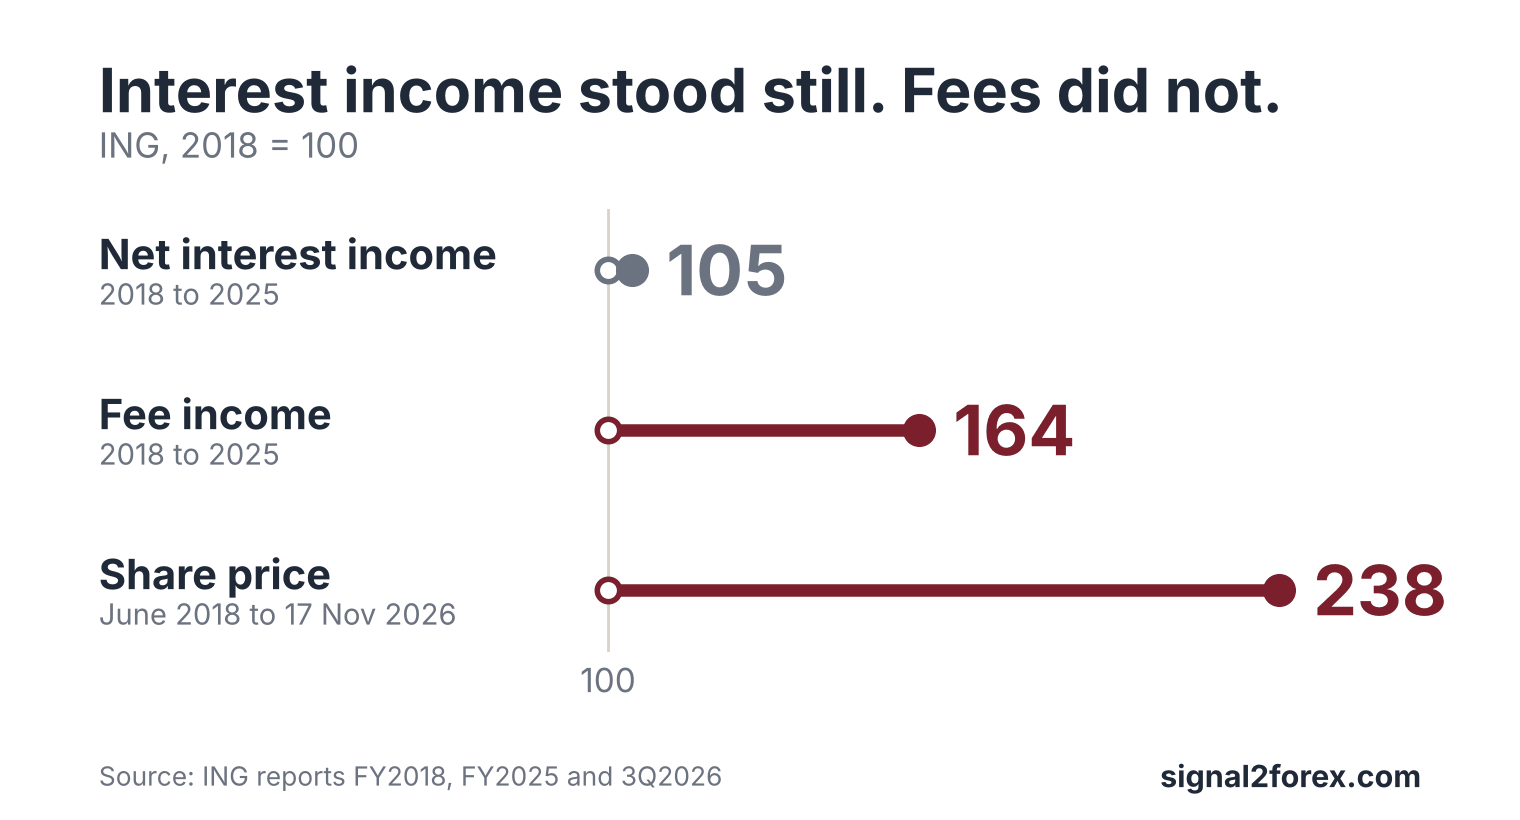
Did insurance do this? I cannot say that. ING explains the growth of fees with more customers and more investment products, and higher interest rates after 2022 did a large part of the work for the share price. Insurance is one line in a longer list. It is not just a product on a shelf but a reason for the customer to stay in the app.
The rule for traders
I do not trade bank shares. My robots trade currencies on the one-hour chart, and my real account is on the YouTube stream of this site. But the story of ING is close to me as an engineer. For this page I checked every number against ING’s own reports, and each of them said the same thing about dependence on one input.
There is another link to currencies. The decisions of the European Central Bank move the margin of every bank in the euro area, and the same decisions move the euro. Will the next change in rates hurt ING less than it did in 2018? I think so, but the next cycle of rate cuts will be the real test.
A forced sale, a failed platform, local partners, subscriptions, fees — all this is one story about a bank that stopped living on one number. The more sources of income a business has, the steadier it stands when interest rates change.
Figures come from ING’s annual results for 2018 and 2025, the ING 2Q2018 share information table, the ING press release of 29 October 2026, the ING and AXA announcements of 13 June 2018, the ING Belgium and NN release of 28 June 2024, the bolttech release of 11 June 2026 and a Reuters report of 10 June 2026.
Uladzimir Leuchankou is a software engineer with a BSc in Finance and the founder of Signal2Forex. He develops the trading robots of this site, the Forex V Portfolio among them, and runs a real account that is streamed on YouTube. The percentages on this page are his own calculation from ING’s published figures, checked on 18 November 2026. Contact: forexfactory1shop@gmail.com.




 Signal2forex.com - Best Forex robots and signals




