
By Uladzimir Leuchankou, founder of Signal2Forex · 5 November 2026
What are Samarkand bonds? Just bonds with the name of an old city on the Silk Road? I suppose that is an answer too. But for me a Samarkand bond is first of all a bet on one currency — the Uzbek soum.
The definition is short. Samarkand bonds are bonds in Uzbek soum that are sold to foreign investors and listed on the London Stock Exchange. The first one came on 18 May 2018 from IFC — the arm of the World Bank Group that lends to private business. I took the numbers below from the IFC press release and from the Central Bank of Uzbekistan.
| Issuer | IFC, rated AAA |
|---|---|
| Size | 80 billion soum — about $10 million |
| Coupon | 9.5% a year |
| Term | 2 years, repaid on 29 May 2020 |
| Listing | London Stock Exchange, 20 June 2018 |
| Use of money | Soum loans to small firms through Hamkorbank |
The idea behind it is simple. A fund in Europe wants a high coupon. A bank in Uzbekistan needs soum for loans, and it does not want a debt in dollars. IFC stands between the two. ING Bank arranged the sale, and three European asset managers took the whole issue.
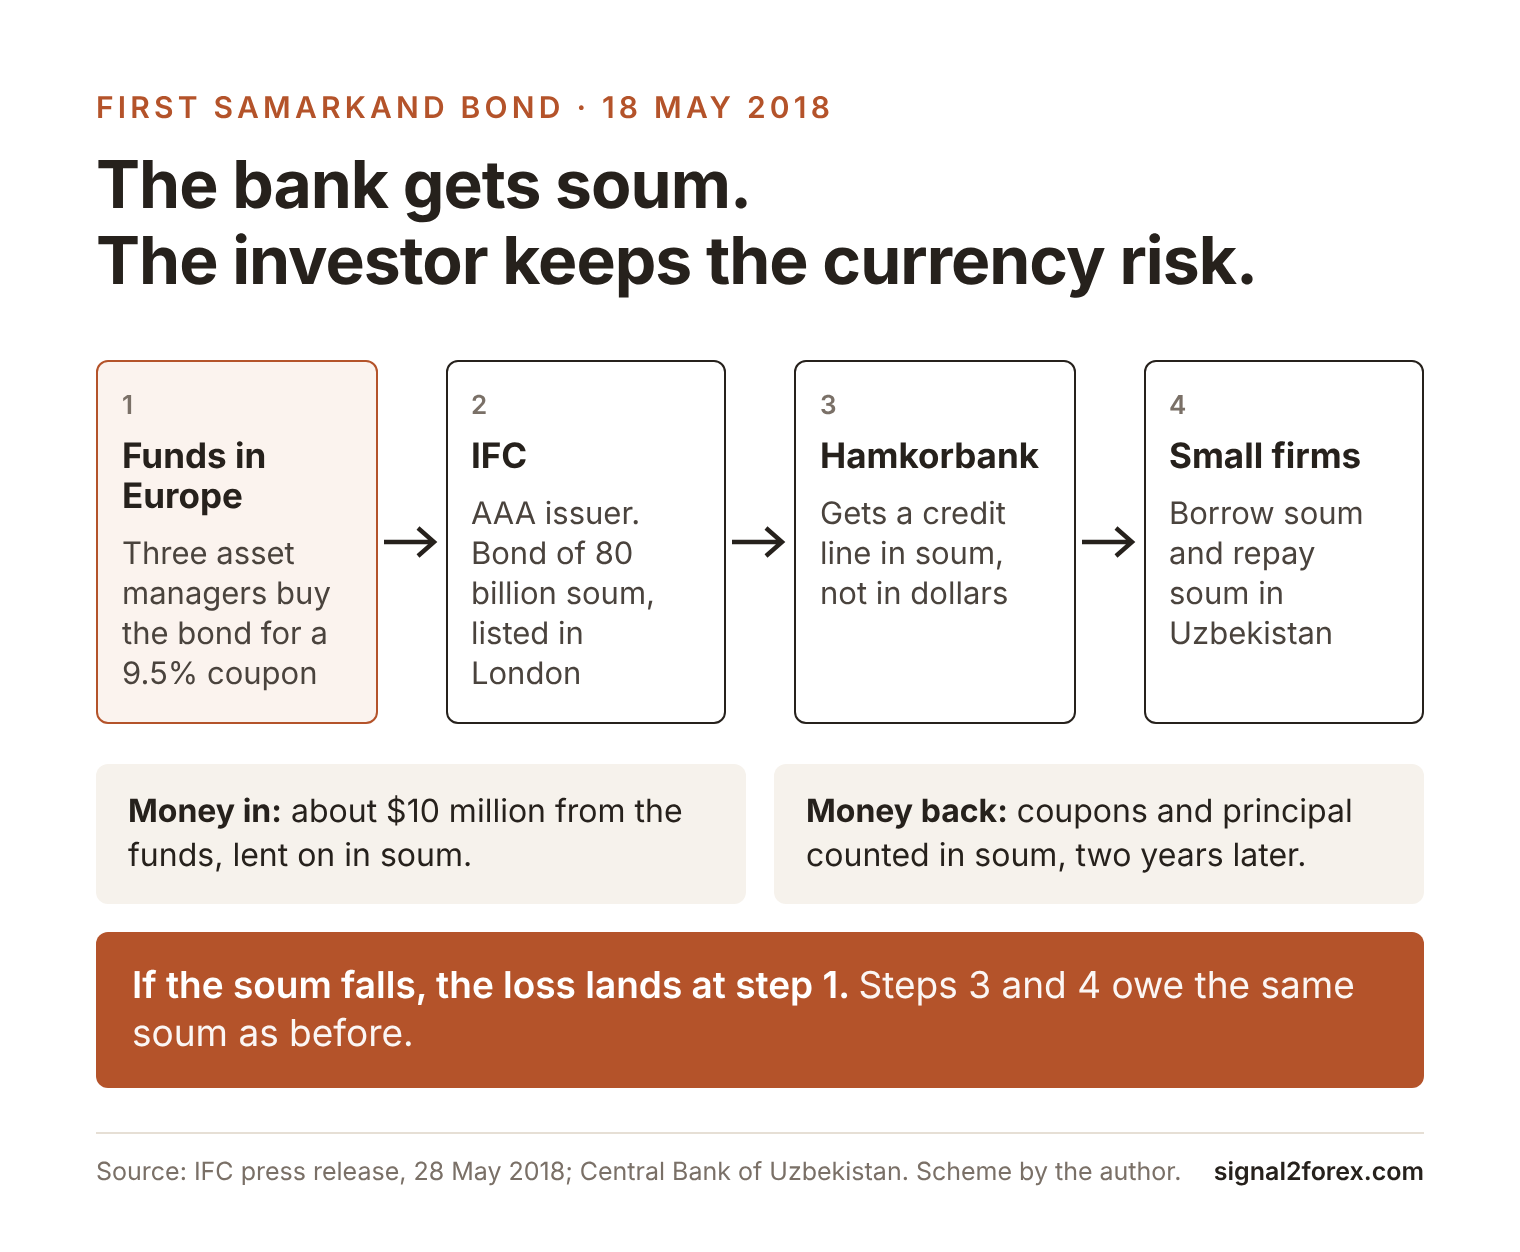
Who carries the currency risk in this chain? The investor — the bank and its clients are free of it. ING said so at the time. In the IFC release its banker Richard Proudlove described the buyers as funds that wanted “an opportunity to get exposure to that currency”.
A name from the Silk Road
Bond markets like nicknames. A yen bond from a foreign issuer is a Samurai bond. Yuan bonds sold outside mainland China are Dim sum bonds. A rupee bond sold abroad is a Masala bond, and a rupiah bond is a Komodo bond. London had listed the last three kinds before 2018, so the soum received a name of its own — Samarkand.
IFC did not stop at one issue. By December 2018 it had sold five, for 476 billion soum in total. This is about $59 million at the average rate of that year. The first four went to Hamkorbank and to Ipak Yuli Bank, with coupons of 9.45% to 9.5%. The exchange still keeps a page for Samarkand bonds and counts more than 470 billion soum raised.
One more thing about the name. Some readers come here in search of a company — a Samarkand trading group, or a fund called Samarkand Capital. This page will not help them. The bonds share only the name of the city with such firms.
Coupon against currency
A coupon of 9.5% looks generous next to a dollar deposit. A soum bond is not only a coupon, though — it is also a position in the soum. So how much of the coupon stays with you in dollars?
I counted it for the first Samarkand bond, with the official rates of the Central Bank of Uzbekistan. In the week of the sale one dollar cost 8,025.83 soum. Put $10,000 into the bond and you hold 80.26 million soum. Two years of coupons add 15.25 million soum.
On 19 May 2020 — ten days before the bond was repaid — the dollar cost 10,129.56 soum. Your 95.51 million soum is now $9,429. The coupons gave 19%. The exchange rate took 20.8%. So the result is a loss of about 5.7% in dollars. On a $100 cent account it is the same — $94.29 comes back.
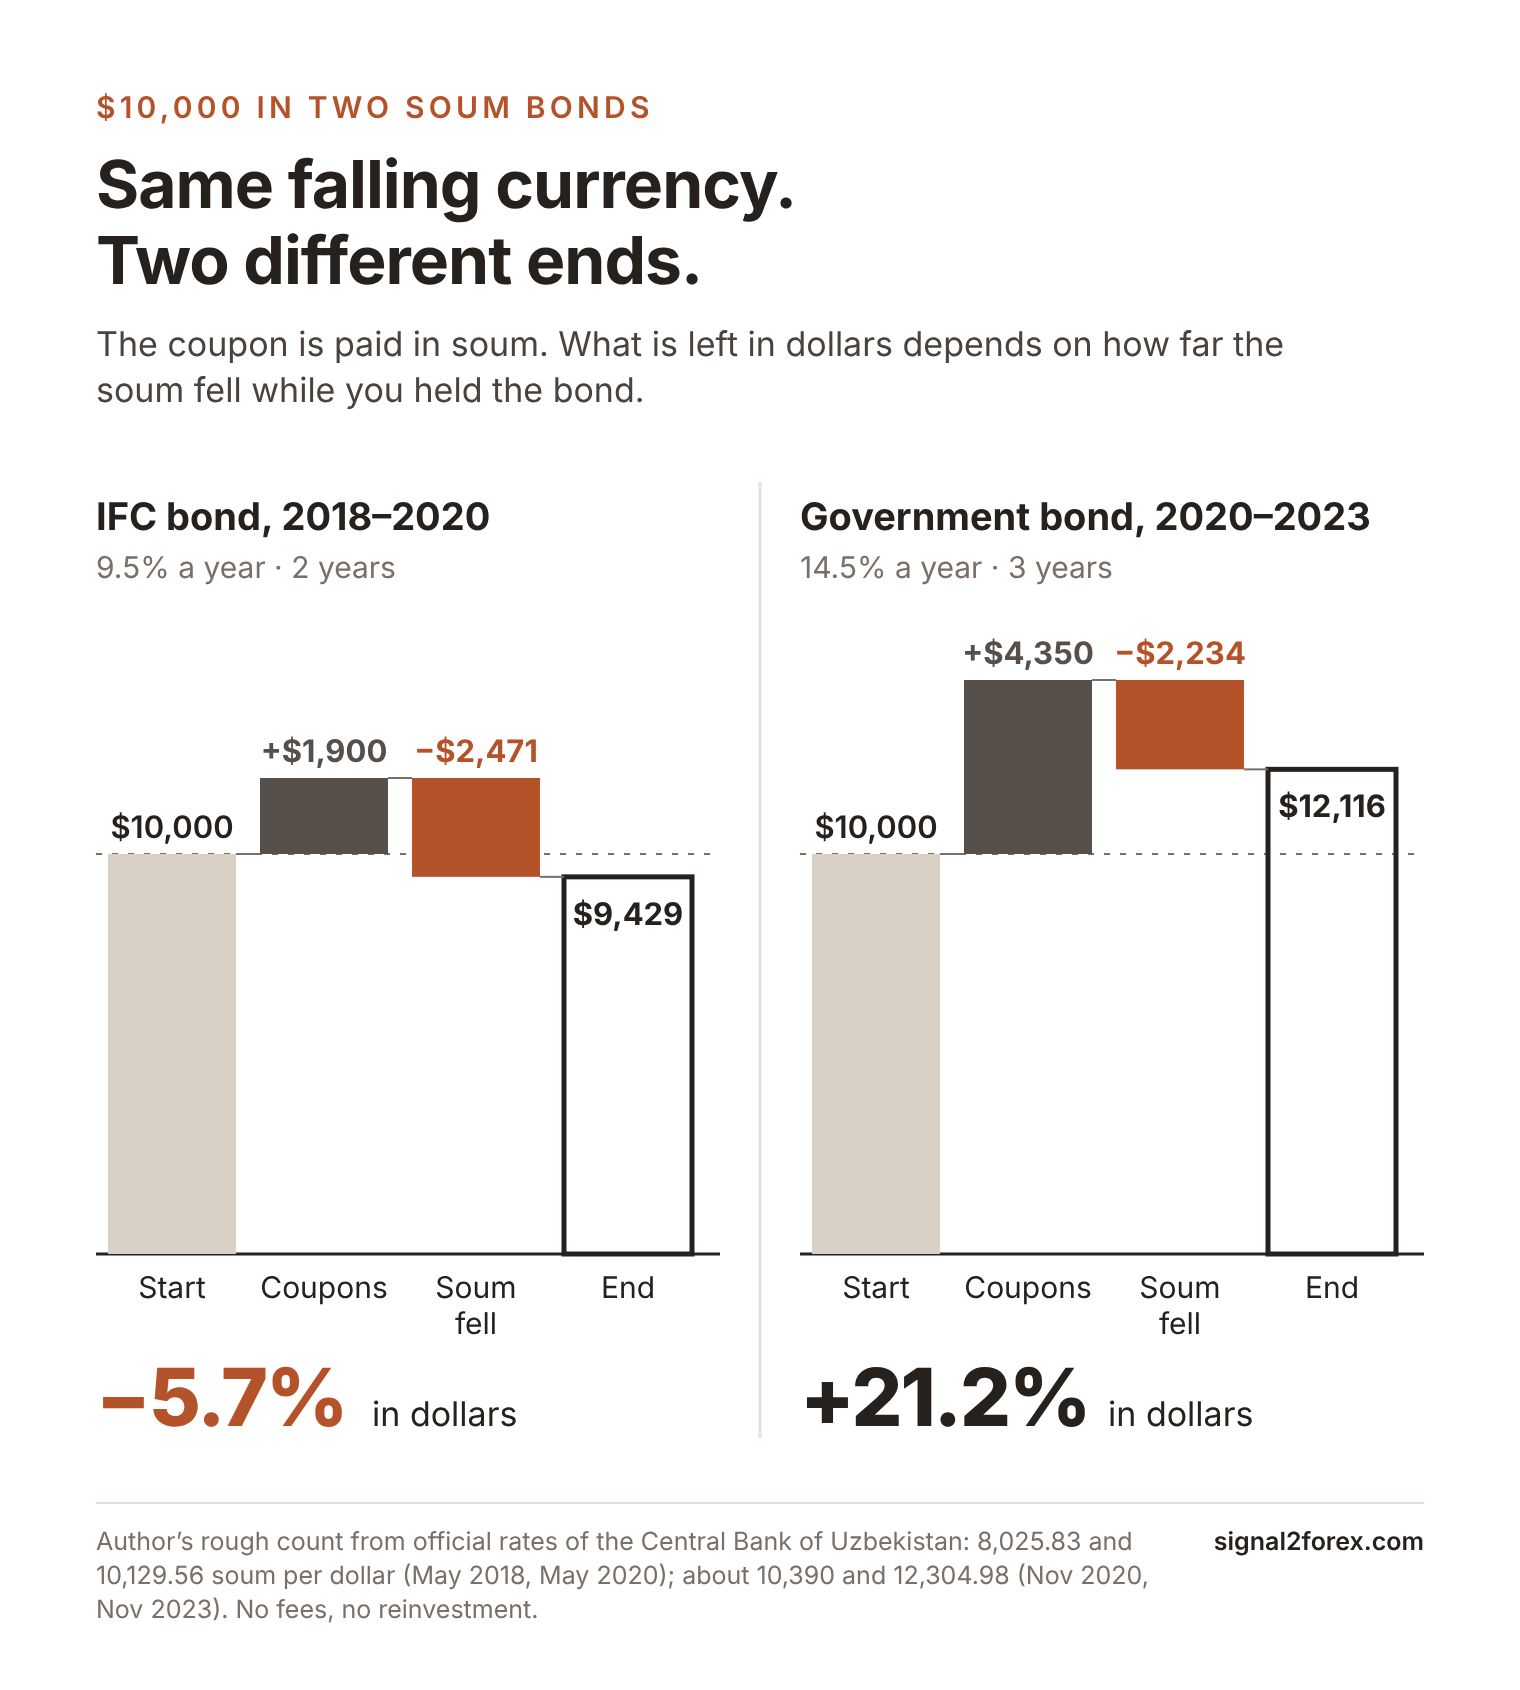
My count is rough. It turns every coupon into dollars at the last rate, and real coupons arrive earlier, at a better rate. So the true loss was a little smaller.
It was still a loss.
There is another soum bond with the opposite result. In November 2020 the government of Uzbekistan sold its own three-year bond in soum — 2 trillion soum at 14.5%. The buyer paid in dollars and received dollars, and only the amount was counted in soum. At the start the dollar cost about 10,390 soum, and three years later 12,304.98 soum.
The soum lost 15.6% in that time. Three years of coupons added 43.5%. A stake of $10,000 became about $12,100 — $121 on a $100 account. The currency fell in both cases, and only the size of the coupon changed the end. If you buy a yield in a foreign currency, you need to count the exchange rate first.
Samarkand bonds after 2018
This page began in March 2019 as a short news note. A month before, on 13 February 2019, Uzbekistan had sold its first dollar Eurobond — $1 billion in two parts, at 4.75% for five years and 5.375% for ten. The question of that spring was plain. Would a market in soum follow?
The officials were careful. Late in 2019 deputy finance minister Odilbek Isakov said he did not expect “large demand for a soum eurobond” next to dollar bonds. He saw it as an add-on. The table shows what happened next.
| Date and issuer | Size in soum | Coupon |
|---|---|---|
| May 2018, IFC | 80 billion | 9.5% |
| Nov 2020, Uzbekistan | 2 trillion | 14.5% |
| Jul 2021, Uzbekistan | 2.5 trillion | 14.0% |
| Oct 2023, Uzbekistan | 4.25 trillion | 16.25% |
| May 2024, Uzbekistan | 3 trillion | 16.625% |
| Feb 2025, Uzbekistan | 6 trillion | 15.5% |
| Apr 2026, Uzbekistan | 12.2 trillion | 12.25% |
The last line is the one I look at. On 1 April 2026 the Ministry of Economy and Finance sold 12.2 trillion soum of three-year bonds — about $1 billion — at 12.25%. Nearly 50 foreign funds sent orders for 23.4 trillion soum. The rate came out 14 basis points — 0.14 of a percentage point — below the rate inside the country. Two years earlier the same kind of bond cost the government 16.625%.
Two more facts belong here. On 25 June 2026 Moody’s moved the rating of Uzbekistan up to Ba2 — it was B1 at the debut in 2019. And since 30 September 2026 the soum bonds of the government are part of the J.P. Morgan GBI-EM index. The ministry says funds with more than $300 billion follow this index.
Are these still Samarkand bonds? By the definition of the exchange — yes, every soum bond sold abroad is one. But the April release of the ministry does not use the nickname. It stayed with the IFC issues of 2018, and I do not know whether IFC will come back with a new one.
The soum since 2017
The soum is a young market currency. Until 5 September 2017 the official rate stood at 4,210 per dollar, and almost nobody could buy dollars at that price. On that day the central bank let the rate go to 8,100.
After that the soum lost value year after year. The average rate was 8,070 in 2018, 10,054 in 2020, 11,050 in 2022 and 12,651 in 2024. Then the line turned. On 5 November 2026 the official rate is 11,935.37 soum per dollar — 5.7% below the average of 2024.
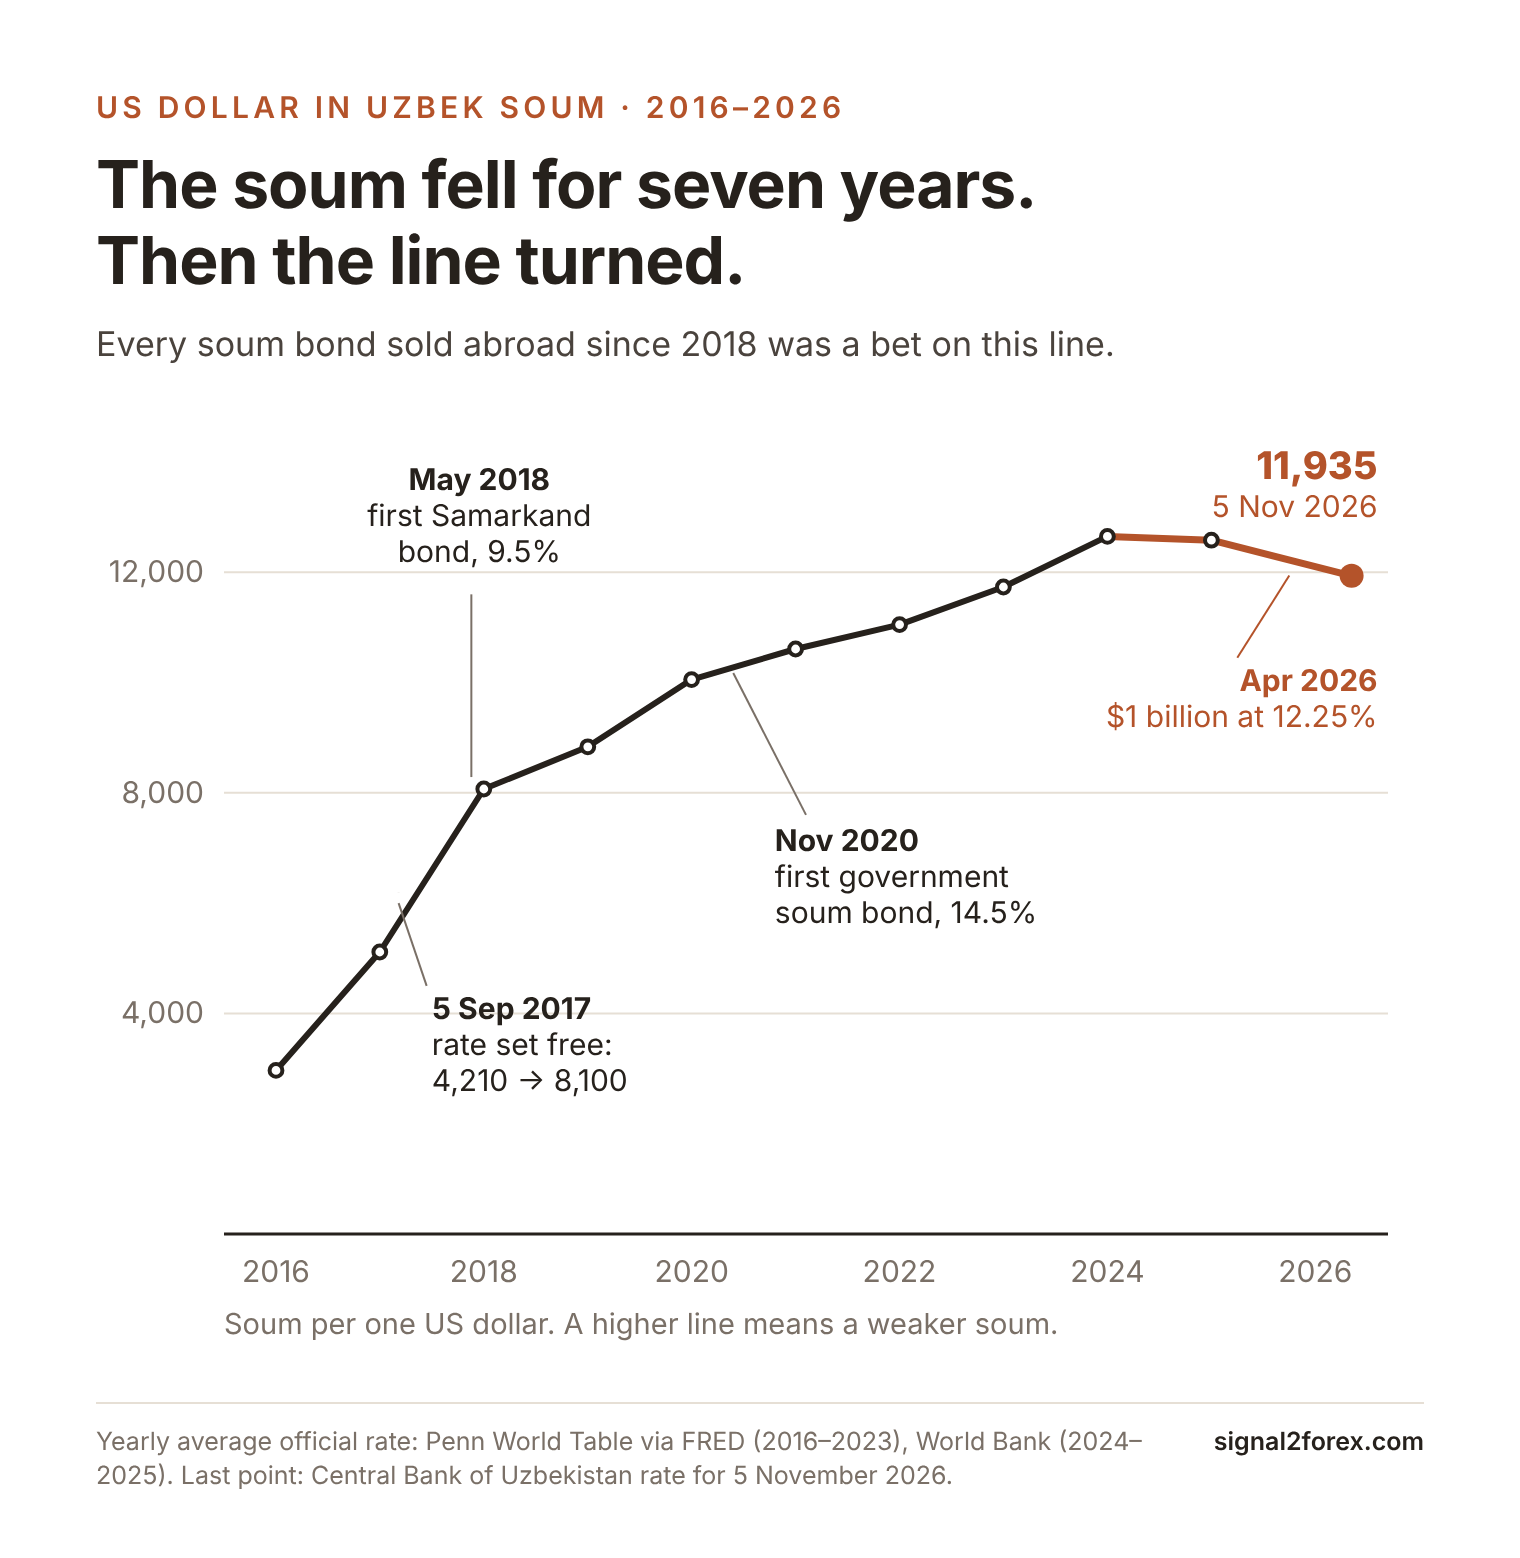
Why did it turn? One reason is easy to see. The central bank keeps money expensive. On 4 November 2026 it held its policy rate at 14% once more, with inflation at 6.4% in September. So the rate stands 7.6 points above inflation. A rate this high not only slows prices, but also makes soum deposits attractive. The bank also raised its inflation forecast for the end of 2026 to about 7%.
A hold with a higher inflation forecast is a hawkish signal. I wrote about this language in the article on hawkish vs dovish central banks. For the soum it means that the high rate stays for now. The bank wants inflation at 5% by the end of 2027.
For a holder of the April 2026 bond this matters more than the coupon itself. The coupons add 36.75% over three years. So the buyer stays in profit in dollars while the dollar costs less than about 16,675 soum in April 2029. Will the dollar stay below this line? We will see in April 2029.
No soum on my screen
Now the part for a forex trader. Can you trade any of this from a retail account? I do not think so. My robots work on 14 pairs — from EUR/USD and USD/JPY to AUD/CAD and CAD/CHF — and the soum is not in any of them.
Its official rate is set in Tashkent, from trades on the local currency exchange. The central bank publishes it once a day — at 16:00 in Tashkent, which is 11:00 GMT — for the next day. One price a day gives a one-hour robot nothing to work with.
Many pages — an older version of this one too — call Samarkand bonds a leading signal for pairs like USD/TRY. I do not agree. The first issue was $10 million. The forex market turns over about $9.6 trillion a day, by the BIS survey of April 2025. A deal of this size cannot lead a market of that size.
What I do take from these bonds is the arithmetic. It is the same on my own account, only smaller. A robot of the Forex V Portfolio trades on the one-hour chart and can keep a position open for several nights. Every night the broker adds a swap or takes it away. A positive swap feels like a small coupon.
But look at the other side of the count. A move of 150 pips against a position costs about $15 on a 0.01 lot of EUR/USD — $1,500 on one standard lot. No swap covers that. My portfolio has a Buy robot and a Sell robot for every pair. So the swap never decides a trade — the price does.
A name from an old trade road, a coupon of 9.5%, a loss of 5.7%, a market that grew from $10 million to $1 billion, a currency that fell for seven years and then turned — all this is one exercise in counting. The more of the return you count before you enter, the steadier you stay when the rate moves.
Figures checked on 5 November 2026 against: IFC press release of 28 May 2018; London Stock Exchange, Samarkand bonds page; Ministry of Economy and Finance of Uzbekistan, release of 2 April 2026; Central Bank of Uzbekistan, official rates and the decision of 4 November 2026; BIS Triennial Survey 2025; Penn World Table and World Bank for the yearly average rates.




 Signal2forex.com - Best Forex robots and signals


